Want to retire decades early? Here’s how the FIRE movement works
What if your last day of work came at 50? Or 45? For some followers of the FIRE movement, even 40 isn’t considered impossible.
FIRE—short for Financial Independence, Retire Early—turns the traditional work-until-your-60s model on its head. Instead of spending most of what they earn and saving gradually for retirement, followers aggressively cut expenses, increase their savings rate, invest the difference, and work toward accumulating enough money that a paycheck becomes optional.
The idea sounds incredibly appealing, but FIRE isn’t simply about being cheap or quitting your job young. Getting there can require years of unusually high savings, disciplined investing, careful planning, and some significant lifestyle tradeoffs.
So how does FIRE actually work, how much money do you need, and is early retirement realistic for ordinary people? Here’s what you should know.
Find your FIRE number
A $1 million portfolio is an appealing milestone, but it isn’t a magic retirement number. Whether it’s enough depends on how much you spend, when you retire, your housing costs, taxes, healthcare expenses, other income sources, and how long your money needs to last.
That’s especially important for FIRE followers, who may be planning for a retirement lasting 40 or 50 years rather than 20. Instead of starting with an arbitrary number, estimate the annual income your desired lifestyle will require and work backward to determine the portfolio that could realistically support it.
Maximize what you earn, not just what you save
There’s a limit to how much you can cut from a budget. There is theoretically much more room to increase what you earn.
Raises, promotions, changing employers, developing higher-paying skills, freelance work, a side business, or other income streams can dramatically increase the amount available to invest. The trick is avoiding lifestyle inflation as income rises. If a $15,000 raise produces $15,000 in new spending, it hasn’t moved financial independence much closer.Maximizing Income Streams
Increasing income streams is fundamental to accelerating progress toward a million-dollar retirement goal. This can be achieved by diversifying income sources, such as seeking promotions or higher-paying job opportunities, starting a side business, or investing in income-generating assets like rental properties or dividend-paying stocks.
The 50/30/20 rule may not be enough for FIRE
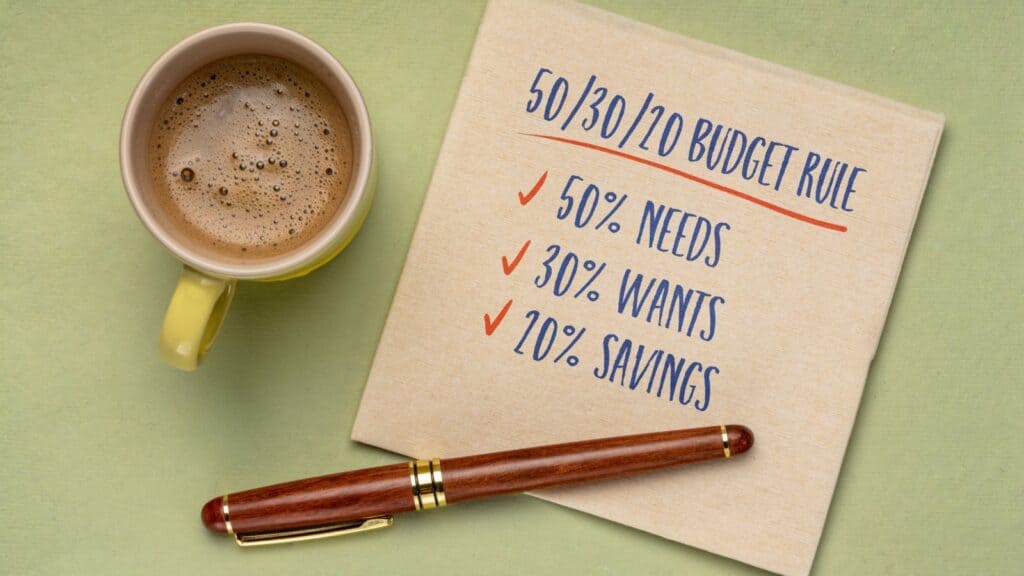
The familiar 50/30/20 budget puts 50% of take-home income toward needs, 30% toward wants, and 20% toward savings and debt repayment. That’s a useful starting point for many households—but FIRE followers often aim to save considerably more.
Why? Your savings rate can affect both sides of the FIRE equation: you’re accumulating investments faster while learning to live on less money. You don’t have to save half your paycheck to benefit from FIRE principles, but increasing your savings rate whenever your circumstances allow can potentially shave years off your timeline.
Frugality should buy freedom, not misery
FIRE-style frugality isn’t supposed to mean never eating out, taking a vacation, or buying something simply because you enjoy it. It’s about deciding which expenses genuinely improve your life and which ones you’re paying almost automatically.
Cutting $5 from something you love may matter less than reconsidering a $700 car payment, expensive housing, recurring subscriptions, or habitual spending you barely notice. Sustainable frugality focuses on value, not deprivation.
Invest for decades, not headlines
Saving money alone generally isn’t enough to build a portfolio capable of funding decades without employment. FIRE plans typically depend on investing for long-term growth.
Diversification can reduce the risk of having too much riding on one company, sector, or asset. Just as important is consistency: regularly investing through good markets and bad ones can be more useful than repeatedly trying to predict what stocks, cryptocurrencies, real estate, or other investments will do next.
Your appropriate investment mix depends on your goals, risk tolerance, and time horizon—and it may need to become more conservative as you approach the point when you’ll rely on the portfolio for income.
Put compound growth on your side
Compound growth means your investment returns can begin generating returns of their own. Given enough time, that snowball effect can become one of the most powerful forces in a long-term financial plan.
That’s why starting earlier can matter enormously. Someone who consistently invests a modest amount for decades may accumulate more than someone who waits and then tries to catch up with much larger contributions. Time isn’t the only ingredient in building wealth, but it’s one you can’t replace later.
Know Your Tax-Advantages
Keeping more of your investment returns can help you reach financial independence faster, making accounts such as 401(k)s, 403(b)s, traditional IRAs, Roth IRAs, and HSAs potentially valuable tools.
But early retirees face an additional challenge: much of their money may need to support them before the traditional retirement-account withdrawal ages. That makes tax planning particularly important. FIRE investors may need a combination of retirement and taxable accounts, along with a strategy for accessing money at different stages of life.
Live below your means — especially when income rises
The gap between what you earn and what you spend is what creates money available for saving and investing.
One of the easiest ways for that gap to disappear is lifestyle creep. A raise leads to a nicer car. A promotion leads to a larger house. Before long, someone earning twice as much may not be saving much more than before.
You don’t need to freeze your lifestyle forever. But deliberately directing part of every raise, bonus, or windfall toward investments can allow your wealth to grow along with your income.
Don’t let high-interest debt sabotage the plan
It’s difficult for investments to build wealth when high-interest debt is simultaneously draining it.
Credit-card balances and other expensive debts can consume money that could otherwise be invested. Paying those balances down can therefore be an important early step toward financial independence. Lower-rate debt, such as some mortgages or student loans, requires a more nuanced calculation; aggressively eliminating every debt isn’t automatically the best financial move.
Protect the plan with emergency savings and insurance
Financial independence isn’t only about accumulating assets. It’s also about protecting yourself from events that could force you to raid those assets.
An emergency fund can absorb expenses such as major repairs, job loss, or unexpected bills without immediately turning to credit cards or selling investments at a bad time. Appropriate health, home or renters, auto, disability, and other insurance can protect against losses too large to comfortably self-fund.
The closer you get to leaving traditional employment, the more important these safeguards become.
Invest in your earning power
One of your most valuable financial assets may be your ability to earn money.
Training, certifications, education, networking, and developing in-demand skills can increase income for years—and those additional earnings can then be invested. But don’t assume every degree or credential will pay for itself. Compare the likely cost with the realistic increase in earnings before taking on substantial debt.
For someone pursuing FIRE, a relatively small investment that substantially raises income can sometimes produce a better return than another round of extreme expense cutting.
Real estate and passive income aren’t automatically passive
Rental property can provide income, diversification, and potential appreciation, which makes real estate attractive to some people pursuing financial independence.
But rental income isn’t free money. Mortgages, property taxes, insurance, vacancies, repairs, management fees, and unexpected expenses all reduce returns. Being a landlord can also require considerably more work than the phrase “passive income” suggests.
Real estate can be one route to financial independence, but it isn’t a requirement—and it shouldn’t be treated as guaranteed income.
Check whether you’re still on track
A FIRE plan created at 30 may look very different by 40.
Income changes. Families grow. Housing costs rise. Markets fall. Health needs emerge. People also simply change their minds about what they want their future to look like.
Review your savings rate, investment allocation, projected spending, taxes, insurance, and target retirement date periodically. Recalculating doesn’t mean the original plan failed. It means you’re planning around your actual life rather than the one you imagined years ago.
Discipline matters, but flexibility may matter more
Reaching financial independence usually requires years of consistent saving and investing. But rigidly following a plan regardless of what happens can be counterproductive.
A job loss may temporarily reduce your savings rate. A booming market shouldn’t automatically convince you to retire earlier. A market downturn near your target date may require another year of work or lower initial spending.
The goal isn’t to execute the original spreadsheet perfectly. It’s to build enough financial resilience that you have choices when life doesn’t follow the spreadsheet.
Know what you’re retiring to
This may be the most important FIRE question of all.
Financial independence tells you how you’ll pay for your life. It doesn’t tell you what that life will contain.
Before making early retirement the ultimate goal, think about what you want your days to look like without work providing structure, identity, social interaction, and purpose. Travel? Family? Volunteering? Starting a business? Creative work? A completely different career?
For many people, the greatest benefit of FIRE isn’t actually retiring at 45. It’s reaching the point where earning a paycheck is no longer the deciding factor in how they spend their time.
Are We Getting Bullied Into Tipping? When To, How Much And When Not To Tip
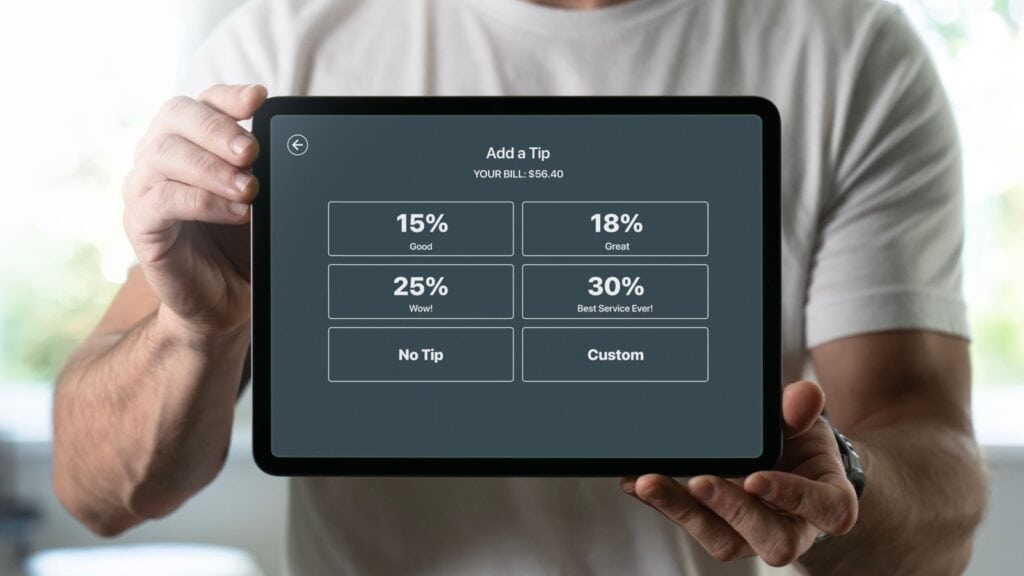
It is happening more and more. You are standing in line at a fast food restaurant or coffee shop, the counter person guides you to the point-of-sale machine and there it is, staring at you. Even at self-checkout machines, a screen comes up suggesting that you tip, complete with an array of amounts, sometimes a dollar amount, other times a percentage. Read: Are We Getting Bullied Into Tipping? When To, How Much And When Not To Tip
9 Of The Most Regretted Purchases People Still Regularly Make
Many people regret trying to keep up with the latest trends, whether it’s buying expensive fashion items, fancy gadgets, or luxury cars; the initial excitement often fades quickly, leaving behind feelings of disappointment. It’s essential to focus on what truly brings long-term satisfaction rather than chasing fleeting trends. Let’s take a look at a few trends and costly items that are best avoided. Read: 9 Of The Most Regretted Purchases People Still Regularly Make